Safety shoes, work gloves, uniforms, helmets and lab coats. In many industries, it is necessary to wear specialised clothing when doing your job. If you as an employee pay for or maintain it yourself, you can in some cases receive a clothing allowance. If you as an employer buy and allocate the clothing to your employees, there may be a tax deduction available. Understand the rules here.
What are clothing allowances and deductions for workwear?
Clothing allowance is a monthly financial compensation often given to employees who work in occupations where they are required to wear specialised workwear or uniforms as part of their job. The purpose of clothing allowance is to help cover the cost of acquiring and maintaining the required workwear.
Clothing allowance is not a fixed rate, but can vary depending on the applicable collective labour agreement. The clothing allowance will appear on your payslip. The allowance is only intended for work clothes, which does not apply to e.g. regular everyday clothes or if there is a special dress code at the workplace that requires you to cover your shoulders and knees, for example.
Some employers provide workwear directly to employees at no extra cost. The employer can get a tax deduction for the purchased clothing if the clothing is intended and necessary for work-related use.
Who is eligible for clothing allowance?
You are eligible for a clothing allowance if:
- You buy and wash your workwear yourself
- You have to buy the clothes yourself but can have them washed at work
- Your employer provides you with clothes but you have to wash them yourself
What types of clothing can you get clothing allowance for?
The type of clothing eligible for clothing allowance depends on the industry and the employer's policy. Clothing allowance is usually intended to cover the cost of work clothes or uniforms that are necessary for the performance of a specific job function. The types of clothing that usually qualify for clothing allowance can include:
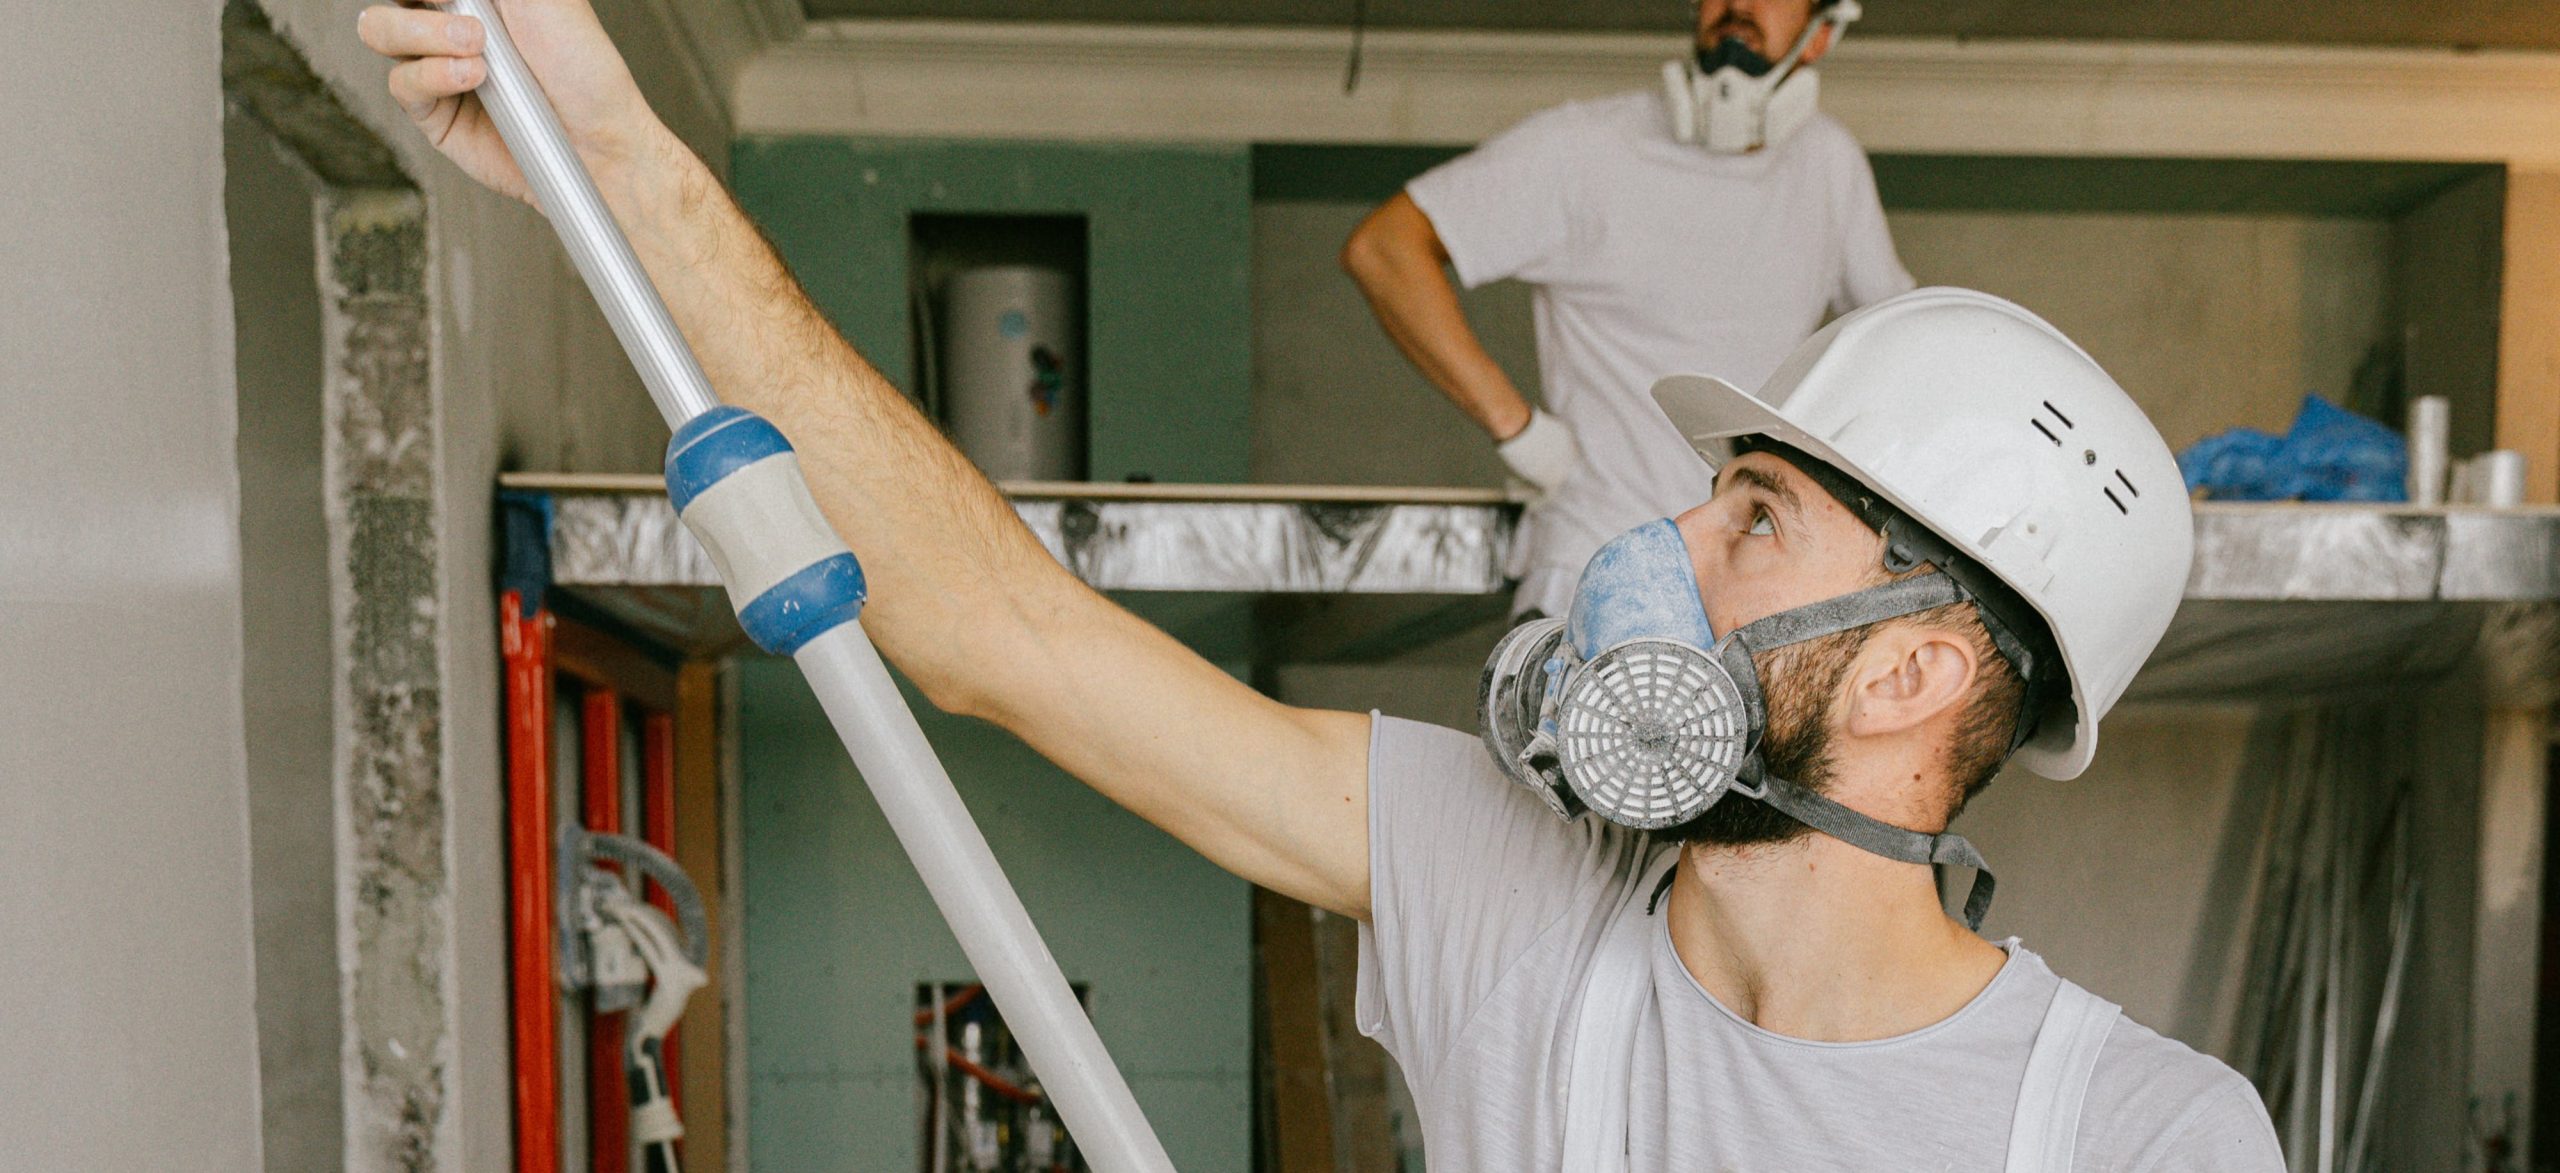
- Workwear: This can include clothing that protects the employee from specific risks or hazards in their work environment. For example, safety shoes, hard hats, overalls, goggles and other safety equipment.
- Uniforms: Uniforms required in industries such as military, police, healthcare, hospitality, and aviation may qualify for clothing allowance.
- Specialised clothing: Some industries may require specialised uniforms or clothing specifically designed for the tasks the employee performs. This could include white lab coats for doctors, workwear for mechanics or uniforms for flight crews.
- Protective equipment: This can include clothing that protects against hazardous chemicals or materials, such as chemical protective suits or radiation protection equipment.
It's important to note that the exact guidelines and types of clothing that qualify for clothing allowance can vary from employer to employer and industry to industry. It's important to understand your employer's policies and possibly consult with your employer's HR department or union to get clarity on what type of clothing qualifies for clothing allowance in your specific situation.
What is the compensation amount?
When companies pay out a cash clothing allowance, the typical range is between £100 and £500 a month before tax. The exact amount depends entirely on the applicable collective agreement, the occupational group and the purpose of the compensation.
The distribution is typically as follows:
- The low range (DKK 100 – 200/month): Usually covers situations where the employee is provided with company clothing or a uniform, but has to take care of the washing and maintenance at home themselves.
- The high range (300 – 500+ DKK/month): Often seen in industries where employees wear their own private clothing, which is subjected to extraordinary wear and tear, dirt, or frequent washing (e.g. in the educational or social sector).
Do I have to pay tax on the clothing allowance?
As a rule, tax is only payable on clothing allowance if the clothing is used privately. However, if the clothing is provided by the employer and can be used privately, only the value of the clothing is taxed. The clothing allowance is tax-free for the employee if the clothing is required for business purposes and is not used during leisure time. To be tax-free, the employer should have clear guidelines on how the clothing allowance should be used.
If the employer chooses to purchase the workwear for the employee, the employer can get tax deduction for the expenses he/she incurs to purchase the necessary work clothing for employees. In order to claim these deductions, it is important that the clothing and the costs associated with it are documented and fulfil certain requirements under tax regulations.
If the clothing is tax-exempt because it can only be used during working hours, all parts of the apparel are typically tax-exempt. This also applies to individual items such as socks and shirts that might otherwise also be used outside of working hours. What is decisive is that the individual pieces of clothing are necessary for the overall uniform. If the value of an employee's work clothing combined with other staff benefits exceeds the annual de minimis limit of £7,600 (2025), you will, however, have to pay tax on the amount.
The Working Environment Act sets requirements for your workwear
Working Environment Act is designed to ensure the health and safety of employees when they work. The law therefore also contains requirements and rules on both mental and physical working conditions in the workplace, including provisions on which conditions require special workwear. As an employer, you should therefore familiarise yourself with the law and ensure that your employees' clothing complies with its provisions.
Sources: Working Environment Act, stadsrevisoren.dk